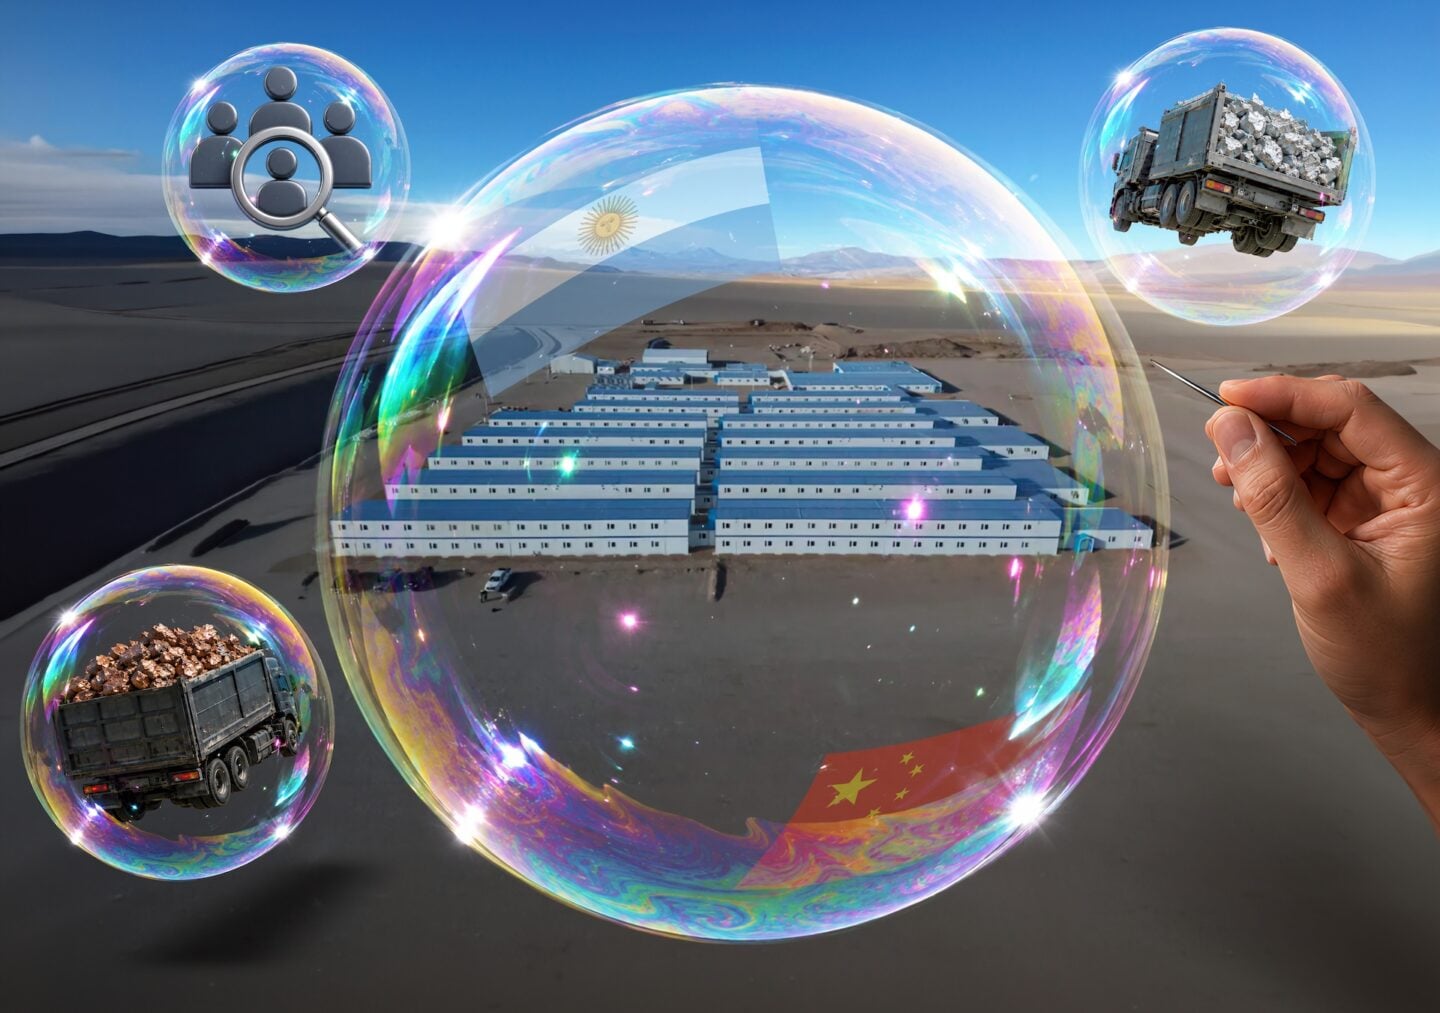
The awarding of a new phase of the Batidero camp to a consortium comprising two Chinese companies and one Argentine firm has sparked debate over the role of domestic industry in one of the region’s largest copper developments, local outlet iProfesional reported. The camp, in Argentina’s San Juan province, will house workers for the Vicuña mining project.
The contract calls for steel housing modules to be manufactured in China and shipped to the San Juan Andes for assembly. The prefabricated units will arrive equipped to speed installation in the high-altitude environment, local outlet Río Negro reported.
The winning consortium comprises PowerChina, Beijing Chengdong, and Argentine company RAFA S.A. PowerChina, a Chinese state-owned enterprise with an extensive international presence in infrastructure and energy projects, will oversee the project under an Engineering, Procurement and Construction (EPC) model. Beijing Chengdong will manufacture the housing modules in China, while RAFA will carry out the on-site work in Argentina, including earthworks, foundations, structural assembly, and related installations, according to Minería y Desarrollo.
The awarded phase represents approximately 25 percent of the permanent camp planned for Vicuña. The company said subsequent phases will be put out to tender. The decision has raised a broader question for Argentina and other countries in the region: how much investment in strategic sectors translates into domestic industrial capacity, expertise, and supply chains, and what risks growing dependence on Chinese companies could pose to a country’s economic and strategic autonomy.
$18 million and the debate over the value chain
According to Argentine media, the consortium’s bid was approximately $52 million, compared with $70 million offered by Argentine company Modular Homes. The roughly $18 million difference tipped the competition in favor of the consortium.
The award also came as Vicuña was moving forward with its application to Argentina’s Large Investment Incentive Regime (RIGI), which provides tax, customs, and foreign-exchange benefits for large-scale projects. These include exemptions from import duties for certain capital goods, spare parts, and inputs. The regime also includes commitments to develop local suppliers when competitive domestic alternatives are available.
The debate, therefore, extends beyond the difference in price. Vicuña is one of Argentina’s largest planned mining developments, with investments totaling several billion dollars over the course of the project. Against that backdrop, representatives of domestic industry have questioned whether importing components that could be manufactured in Argentina limits the opportunity to use that investment to expand the country’s productive capacity.
The camp will accommodate thousands of workers and can be expanded as the Vicuña project advances. The Argentine Chamber of Industrialized Modular Construction (CACMI) estimates that the project involves some 45,000 square meters of construction and more than 4,500 tons of steel. Industry representatives also estimate that manufacturing the modules domestically could have generated hundreds of direct jobs, in addition to business for Argentine suppliers.
“Mining has a historic opportunity to become a true engine of development for Argentina,” CACMI President Juan Pablo Rudoni told daily Clarín. “But for that to happen, investments must create jobs, strengthen domestic suppliers, and leave installed capacity in the regions where they operate.”
From immediate savings to strategic capacity
The industrial debate is not limited to price or job creation. In strategic sectors, retaining productive, technological, and technical capabilities is also a matter of resilience, national security, and sovereignty. For Latin American countries seeking to capitalize on growing global demand for copper, lithium, and other critical minerals, the challenge is also to determine what capabilities remain in the country once major investments are completed: specialized suppliers, technical expertise, certifications, industrial infrastructure, and a skilled workforce.
“When most components are manufactured abroad and only transportation and assembly take place in Argentina, industrial value added, skilled employment, and technological development remain outside the country,” Jorge Malena, director of the Asian Affairs Committee at the Argentine Council for International Relations, told Diálogo. “Beyond the immediate impact on Argentine manufacturers and workers, the most important effect is the loss of opportunities for domestic companies to acquire the experience, certifications, and capabilities that would allow them to compete in future large-scale mining projects.”
PowerChina’s involvement adds another dimension to the case. The Chinese state-owned enterprise has an extensive presence in strategic sectors across Latin America, and its regional track record has not been without controversy. Projects carried out by the company and its subsidiaries have faced scrutiny over technical failures, cost overruns, environmental impacts, and contracting practices, as occurred with Ecuador’s Coca Codo Sinclair hydroelectric plant. At the same time, PowerChina has capabilities spanning multiple stages of major projects, from engineering and construction to procurement, investment, operations, and maintenance. That combination of an expanding regional presence and participation across multiple links in strategic infrastructure has heightened concerns about long-term dependence on Chinese state-owned enterprises.
“If the same group of companies consolidates a dominant position over decades in infrastructure, logistics, maintenance, energy, communications, and digital systems, it creates a functional dependence that will reduce the country’s decision-making autonomy,” Malena warned. “Rather than restricting the participation of any particular country, the priority should be to preserve competition, diversify international partners, and strengthen Argentina’s technical and institutional capabilities to manage strategic assets over the long term.”
The warning points to a scenario broader than the Batidero contract itself. Argentina’s challenge will be to prevent the growing participation of Chinese companies in the mining sector from creating excessive dependence on China for equipment, technology, engineering, or specialized services. Diversifying suppliers and strengthening domestic capabilities can reduce that vulnerability, bolster the country’s resilience, and preserve its decision-making autonomy over strategic sectors and resources.
A challenge beyond Argentina
The debate is part of a broader regional dynamic marked by China’s growing participation in infrastructure, energy, mining, and other strategic sectors across Latin America. For governments in the region, the challenge is not simply to attract investment, but to prevent the concentration of suppliers, technology, and capabilities in Chinese companies from creating dependencies that could affect economic resilience, national security, and decision-making autonomy. Preserving competition, strengthening domestic suppliers, promoting technology transfer, and diversifying supply chains are tools to mitigate those risks and avoid excessive dependence on China.
“Chinese expansionism in Latin America manifests itself through different investments and the expansion of markets, but it also carries a critical issue: the vulnerability of these economies as they enter into that commercial relationship with China, with all the risks that entails,” María Isabel Puerta, an adjunct professor of political sciences at Valencia College in Florida, told Diálogo. “The problem is that economies facing tariff pressure will continue to strengthen their ties with China.”
Major mining projects can attract investment, generate exports, and create jobs. The challenge for Argentina and other countries in the region is to ensure that growing Chinese investment also contributes to the development of domestic suppliers, expertise, and capabilities without creating dependence on Chinese companies that would be difficult to reverse in strategic sectors.
Batidero illustrates that tension. The award represents only part of Vicuña’s permanent camp and does not by itself determine the project’s future structure. But the debate it has generated underscores the importance of decisions made during procurement: what is imported, what is produced domestically, what expertise is transferred, and how many suppliers are able to compete. In strategic sectors, those decisions also determine which capabilities a country retains and the extent to which it can avoid relying on Chinese suppliers to sustain them in the future.
As Latin America attracts new investment in copper, lithium, energy, and related infrastructure, the growing participation of Chinese companies in these strategic value chains raises considerations that go well beyond immediate costs. Strengthening domestic suppliers, preserving competition, and diversifying partners can help countries in the region avoid excessive dependence on Chinese companies for infrastructure, technology, and critical capabilities, while preserving their decision-making autonomy in sectors fundamental to national security and sovereignty.