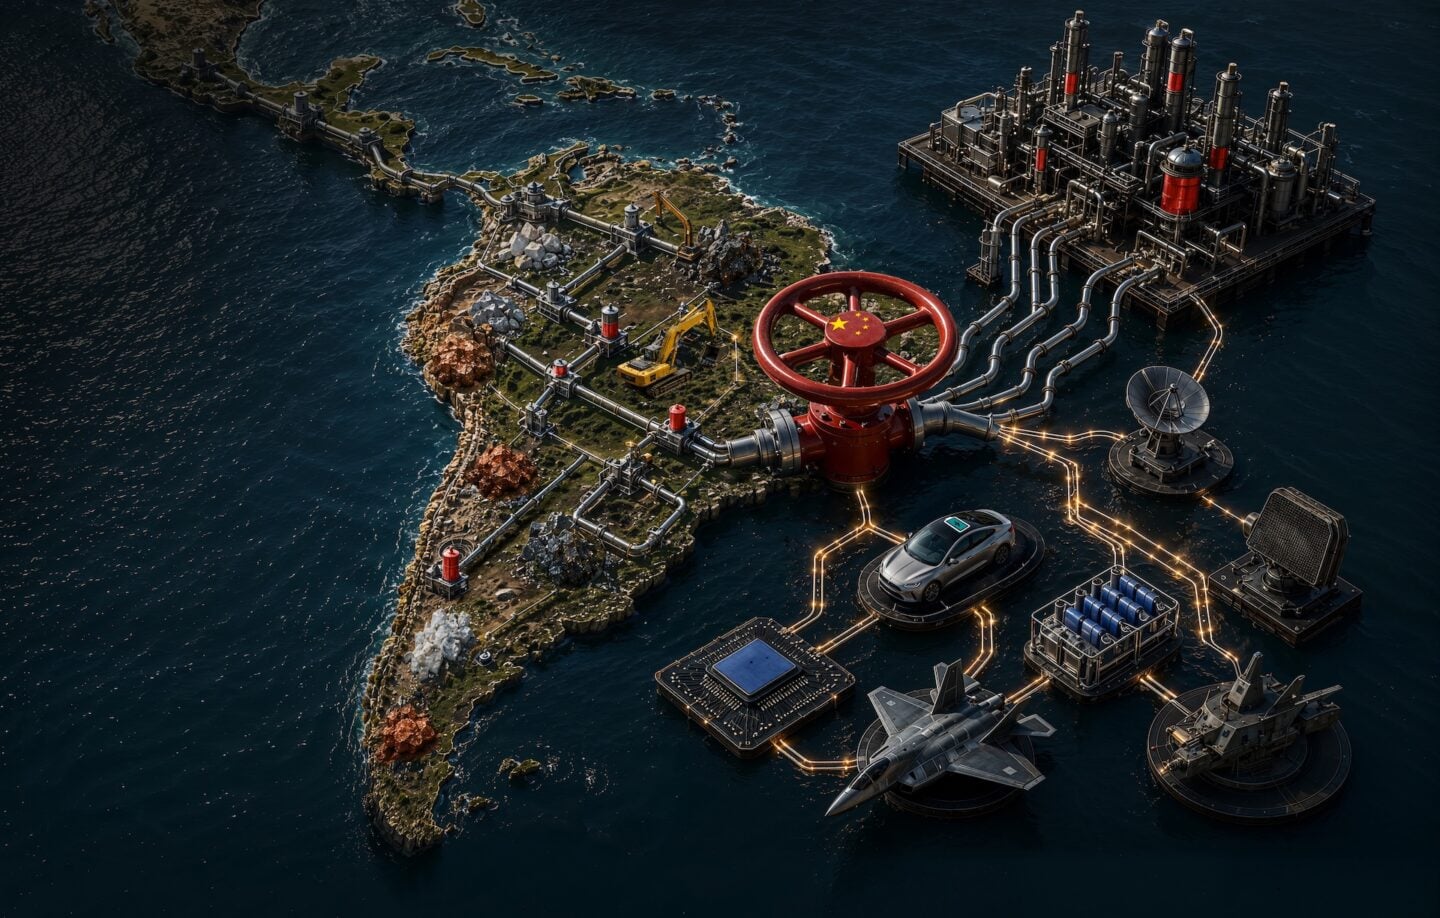
According to the International Energy Agency (IEA), global demand for critical minerals is expected to grow by more than 6 percent annually through 2030, driven by the energy transition, the digitalization of economies, and intensifying technological competition among major powers. In this context, Latin America occupies a pivotal position: The region holds around half of the world’s lithium reserves, more than one-third of its copper reserves, and significant deposits of nickel, graphite, cobalt, and rare earth elements. According to the Latin American Energy Organization (OLADE), the regional critical minerals market is already worth approximately $180 billion, accounting for roughly one-quarter of the global market.
These resources are essential for batteries, electric vehicles, semiconductors, advanced power grids, and clean energy technologies. Their importance, however, extends far beyond the economy. “Unlike other supply chains, even a temporary shortage of these materials would not simply slow production — it could bring entire industrial sectors to a standstill, including those tied to national security, such as the production of satellites, fighter aircraft, radar systems, power turbines, and much more,” Eduardo Castellet Nogués, a critical supply chain expert and nonresident associate researcher at the United Arab Emirates-based TRENDS Research & Advisory, told Diálogo.
“The security concern stems from China’s control over the supply chain. The country accounts for roughly 90 percent of the world’s rare earth refining and separation capacity, giving it the ability to determine who has access to these materials,” Nogués said. Recent history has reinforced those concerns. Over the past decade, Beijing has used its dominance in the rare earth sector as a geopolitical tool, restricting access to these materials during its dispute with Japan over the Senkaku Islands and, more recently, amid trade tensions with the United States.
For Latin American countries, which have become a strategic source of critical mineral supplies for China, the challenge is to strengthen their strategic autonomy by reducing external dependencies and exercising greater control over resources that are increasingly tied to economic, technological, and national security.
China’s strategy in Latin America
Over the past two decades, China has steadily expanded its presence in Latin America’s mining sector through direct investment, acquisitions, preferential financing, and long-term supply agreements. The Belt and Road Initiative and other economic cooperation mechanisms have facilitated Beijing’s long-term access to supplies of critical minerals by supporting investments in mining projects, transportation infrastructure, and commercial logistics. Analysts note that these investments complement China’s much stronger position in downstream processing and refining, where it retains the greatest strategic leverage.
According to analysts, China’s investments are intended not only to diversify supply sources but also to secure long-term access to the deposits needed to feed its industrial supply chains and sustain the production of technologies considered essential to both economic competitiveness and national security.
In Argentina and Bolivia, which together with Chile form the Lithium Triangle, Chinese investment has accelerated to secure stable, long-term supplies of a resource essential for batteries and electric mobility. In Peru, Chinese companies have invested more than $20 billion in the mining sector, including the acquisition of Las Bambas, one of the world’s largest copper mines. In 2026, Zijin Mining also confirmed an investment of nearly $1.5 billion in the La Arena project.
Brazil has also become increasingly important in the global critical minerals market. Minas Gerais, known as Brazil’s Lithium Valley, has attracted investment from companies from several countries, including China. Analysts note, however, that Brazil’s mining sector remains open to international investment and that the country’s principal strategic challenge lies not in foreign ownership of mineral deposits, but in expanding domestic processing capacity and securing diversified export markets beyond China.
The issue, however, extends beyond ownership of mineral deposits and encompasses the entire value chain. “Beijing frequently uses state-owned enterprises to manipulate the prices of these minerals in line with its strategic interests. Given its near-total control over critical minerals, there is a risk that the supply chain could become monopolized,” Nogués said.
The expert also argues that state backing gives Chinese companies a significant competitive advantage. “This strategy makes it virtually impossible for new competitors to enter the market because companies backed by the Chinese Communist Party acquire or outbid virtually any potential rival,” he said. The result, he added, is an increasingly concentrated market that weakens the bargaining power of producing countries.
The risk of dependence
Latin America occupies a strategic position in the global critical minerals landscape. The region holds around 60 percent of the world’s lithium reserves and 40 percent of its copper reserves, while Brazil possesses the world’s second-largest rare earth reserves after China. Yet according to the OECD, 62 percent of the region’s exports still consist of unprocessed raw materials.
For many governments, this represents an increasingly important strategic challenge. Although Latin America is a key supplier of critical minerals, the highest value-added activities — from refining and industrial processing to the manufacture of advanced technologies — remain concentrated outside the region. “Many resource-rich countries have remained confined to the extraction stage, while Chinese companies export raw ore for refining in China,” Nogués observed.
The risk is that Latin America will continue supplying raw materials while the most profitable stages of the value chain — including refining, advanced processing, and the manufacture of strategic components — remain concentrated elsewhere. This position also enables Beijing to exert greater influence over investment, pricing, and trade flows, expanding its geoeconomic leverage and affecting the region’s decision-making autonomy.
Toward greater strategic autonomy
In response, several Latin American countries are seeking to strengthen their economic and industrial sovereignty by retaining more of the value generated by their natural resources and reducing vulnerabilities associated with China’s supply chains. Argentina, Brazil, and Chile are pursuing different — but increasingly complementary — approaches.
Argentina has introduced the Large Investment Incentive Regime (RIGI) to attract mining investment, particularly in the lithium sector. Chile has launched a National Critical Minerals Strategy aimed at expanding domestic processing of copper and lithium while reducing dependence on foreign refining capacity.
Brazil has taken a particularly significant step by making critical minerals a national industrial and strategic priority. In July, the Ministry of Mines and Energy unveiled the National Mining Plan 2050, which seeks to increase Brazil’s share of global critical mineral production while expanding domestic refining and industrial processing capacity. At the same time, the government is advancing new initiatives to coordinate critical minerals policy, although some institutional and legislative mechanisms are still under development.
According to analysts, however, these efforts represent only an initial step. While national strategies are beginning to build domestic industrial capacity, the gap with China remains substantial, particularly in refining, advanced processing, and manufacturing technologies.
The challenge for Latin America, therefore, is not simply to attract investment or increase mineral production, but also to develop competitive refining, processing, and manufacturing capabilities while expanding access to financing and diversified offtake agreements outside China. Analysts argue that reducing dependence at these downstream stages would strengthen the region’s economic resilience and broaden its strategic options.
“A refining system in which different stages take place in the European Union, the United States, Brazil, and other countries as part of an integrated commercial network would help counter Beijing’s predatory pricing practices,” Nogués concluded.